Real Estate and *stuff *
A real person helping real people with real estate
You can scroll the shelf using ← and → keys
You can scroll the shelf using ← and → keys
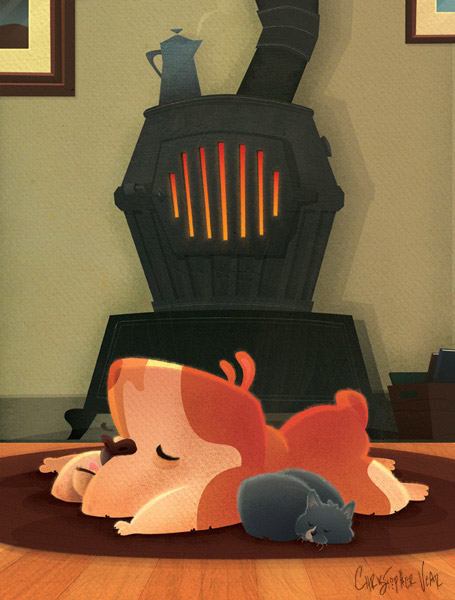 Yes! The last one of the year at 298 New Boston Road in Sturbridge. Today at noon until 1pm. I had so many showing requests with the new price that I am throwing open the doors and lighting a fire!
Here is your chance to see this unique log cabin on nearly five acres that borders Wells State Park. This is a one-of-kind house that needs a new owner to love and care it for as my seller’s have. Within just a few quick miles and you are at the turnpike making this is a great pick for the buyer that needs to commute.
Some of the many features:
Can’t make it during the open house hours? Call me – there are private buyer showings both before and after so we can schedule you in. Did I mention that the hot cocoa has EXTRA marshmallows?
Click here to see the full listing or the video tour.
 Foreclosure may seem like someone else’s problem, but when it happens in your neighborhood, it’s going to cost you money, too.
Each foreclosure within 660 feet (1/8th mile) of your house can drop your home’s value by a factor of almost 0.75%, according to the Center for Responsible Lending, a consumer watchdog group.
The closer a foreclosure is to your house, the bigger the impact. A university of Connecticut study suggests one foreclosure within 300 feet of your home will lower your property value by 1%.
If you live in a neighborhood with few vacant homes and a foreclosure occurs within 250 feet, a University of California, Berkeley study suggests you could lose 2.2% of your home value.
Some people think the homeowners facing foreclosure got themselves into trouble because they bought more house than they could afford with toxic mortgages for which they never should have been approved. At least one study of the 2007 and 2008 foreclosure crisis suggests that was indeed the case.
Even if you don’t feel compassion for those facing foreclosure, you might feel sorry for yourself. Homebuyers and mortgage lenders use foreclosures as comparable properties to value your home when you sell or refinance. And the discount at which foreclosures sell is a hefty 27% on average.
Although most appraisers adjust the value of your home upward compared with a foreclosure, a homebuyer may consider the foreclosure equally valuable to your home and base his offer on that instead of your property’s real worth. If that happens, your real estate agent can argue that non-distress sale comparables and better condition make your property worth more.
Drops in property values brought on by foreclosures don’t just hurt your property value; they also cut away at the whole property tax base, the source of revenue for local government. Elected officials then have to either charge you higher taxes or cut services to make up for the shortfall.
To limit foreclosure damage in your community, ask local officials to pass laws forcing lenders to maintain the properties they now own and to pay the taxes and homeowners association dues on them.
If the town isn’t forcing lenders to maintain a foreclosure in your neighborhood, organize a volunteer effort to cut and trim the shrubs at vacant houses on a round-robin basis, and report vandals or squatters to the police. A well-kept foreclosed home will attract more buyers than one with a weed-filled yard. Take trespassing laws into account as you organize your effort.
If you’re selling or refinancing and the appraiser uses foreclosures as comparable sales to determine the value of your property, ask your real estate agent to make sure the appraiser accounts for the distressed nature of those sales and the condition of the properties as they compare to yours. Ask your agent to seek out other comparable sales the appraiser might have missed, which show your home in a much better light.
 It’s Black Friday…and when it comes to real estate, everything seems to be on sale this holiday season. Getting a good discount on your largest purchase is the financial equivalent of fire sale pricing on a million everyday purchases. If you’re the type who salivates over a 30 percent department store sale or the $4 in bonus bucks you get at the drugstore, these 5 Ways Real Estate is on Sale This Black Friday might literally put you over the moon!
1) Homes. Word on the street is that home prices have now rolled back to 2003 levels. That’s right – if you’re one of those folks who always thought you were born too late to get a great price on your home, 40 (or however old you are) is the new 32 (or however old you are minus about 7 years). Of course, remember, real estate is hyperlocal. That just means that it varies from market to market. It’s a strong buyer’s market everywhere, relative to five years ago, but what that means for your situation will vary from market to market. In San Francisco, that means prices only rose about 11 percent last year, not 30 percent, and buyers may only have to compete with 5 other offers, rather than 25. In cities that have been foreclosure hot spots, on the other hand, prices may have dropped by as much as 50 or even 60 percent since their peak, circa 2006. Everywhere, though, homes are on sale relative to what they were a few years ago.
Since most of your fellow Americans will spend their Black Friday shopping for iPhones and Pillow Pets, they won’t be shopping for homes. The low numbers of active, qualified buyers hunting for homes during the holiday season may make some sellers even more motivated to negotiate a good deal with you! The latest Trulia price reduction report showed that a record-high 27 percent of homes listed for sale on Trulia as of November 1st had at least one price cut – in some cities, 33 percent, 39 percent – even 46 percent of the homes for sale had already been discounted by their sellers. Sellers who are serious about getting their homes sold are putting them on sale this season.
Note to buyers – some homes’ list prices already reflect a great discount. To know whether you’re getting a good deal, check your negotiated sale price against the fair market value of the home (i.e., the recent sales prices of similar, nearby homes – ask your broker or agent to help you figure this out). It is not always the case that you must have a huge discount off the list price for a home to represent a good deal!
2) Property Taxes. Many a buyer isn’t aware, but in most places and most cases, property taxes are determined by the price you pay for your home! So, if you get your home for a “sale” price, you’ll automatically be getting a sale on your property taxes as well!
3) Interest Rates. So, last week, rates went up. We can no longer say they are at historic lows. But seriously, people – they are still sub 4.5 percent on a 30-year fixed; even lower on 15-year loans. Rates may not be the lowest we’ve ever seen them, but they are still very, very low. Chances that they’ll stay that way through the holidays? Strong.
As we’ve already discussed, the holiday decline in numbers of buyers may motivate some sellers to cut good deals. What’s more, sellers who have their homes on the market during the holidays tend to be the most motivated sellers anyway – less motivated sellers would rather not have buyers tracking rain and mud into their homes while they host holiday dinners and guests, or are trying to relax during their time off work. The best way to make your own sale on interest rates is to ask a motivated seller to “pay a point” for you. Some sellers might be willing to credit you the cash at closing to buy your interest rate down. Your mortgage professional can brief you on how much your rate (and, correspondingly, your monthly payment) will decrease for every “point” (1% of your loan amount) you pay; then, when you make an offer, include the amount you need to buy your interest rate down in your offer. Most brokers and agents would do this by requesting a closing cost credit that covers/includes the cost of the interest rate buy down.
4) Closing Cost Credits. More than most holiday buys, real estate costs quite a bit of money to purchase. There are loan origination fees, title insurance costs, escrow fees and even transfer taxes charged just for the privilege of buying a home. You know those Black Friday retailers who offer to pay the sales tax for you? Well, some home sellers take a similar tack, offering to cover some or all of the transaction costs their home’s buyer will incur. Lenders vary, but most will limit the closing cost credit from sellers to 3 percent of the home’s sale price; check with your agent and your mortgage broker about lender guidelines before you write your offer, if you plan to ask “your” home’s seller to cover some of your closing costs.
5) “Included” Items. Some of the best Black Friday sale can include a bonus item the retailer throws in! Same goes for real estate; some sellers don’t have much room to go down on the price, but may be able to include some personal property in the sale. Many buyers relish the thought of moving in to a home complete with new appliances, wall-mounted flat-screen televisions, furniture that suits the space exceptionally well. Some sellers get even more outrageous with this; I recently read a report of a Connecticut seller who threw in – get this – another whole property (their Florida vacation condo), with their home, just to get it sold. Check with your broker or agent and your mortgage pro to make sure any included items won’t run afoul of appraisal or lender guidelines.
With all that said, neither the promise of a great deal, nor the fear of losing out on one! – should be the primary motivator for you making the massive life and financial commitment to buying a home. Buyers should move forward with the project of buying a home when – and only when – it makes sense for their lives, their vision of their future, their families, their jobs and their finances.
But if you’ve already decided you’re ready to buy and have just been waiting for the bottom of the market, the weather to warm up or the mood to strike – these Black Friday (and Saturday, and Sunday) deals on real estate can be a good reason to activate yourself and put your home buying plans in play.
Looking for a great new home? Sign up with a property organizer here to help you!
It’s nice to know that there are options for home ownership after a foreclosure but it’s even better to know that there are options prior to foreclosure. If you are facing foreclosure, contact a member of our Stop Foreclosure Team at RE/MAX Professional Associates. You might be able to avoid it all together. If you have already been through it, this article can give you some steps to becoming a home owner again. I can recommend a mortgage broker in your area and put you back on the path to becoming a home owner again.
 Foreclosure is just a one-time event–with discipline and perseverance, you can get a mortgage and become a homeowner again.
Did you fall into foreclosure because of the lack of a steady job? If you did, the first step toward homeownership after foreclosure is finding and holding one. And if you already have one–stick with it, unless you can move to a better one. Note that potential lenders will require stable employment before they’ll give you a new mortgage loan after a foreclosure. Even if it means taking a lower-paying job, it’s worth it.
Establish a safety net. Financial planners generally recommend three to six months of living expenses in a liquid account, but since you’re coming out of foreclosure, six is a minimum to show stability and that you’re able to pay your bills–including your mortgage–for an extended period if you lose your job.
This is the hardest and most time-consuming part. After foreclosure, your credit score, according to myFICO, probably dropped by about 150 points. You’ll need to raise it back up with perseverance.
Pay bills on time and keep your credit card balances below maximum levels. The foreclosure will stay on your credit report for seven years, but if you prove your money management skills have matured, it will become less of a red mark as years go by.
Tip: Consult a housing counselor. The U.S. Department of Housing and Urban Development offers free housing counseling for distressed homeowners with a foreclosure in their past. A counselor can help you with money management and budgeting. Counseling works–an evaluation of a program in Indianapolis discovered that credit scores greatly improved because of education and counseling, and increased average borrowing power by $4,500 per family.
Normally, you would have to wait seven years after foreclosure before you can apply for a new mortgage under Fannie Mae rules. (Fannie Mae changes rules frequently. You can check the latest rules at Fannie Mae’s site.)
However, you might wait only three years if you can show extenuating circumstances for your foreclosure, which are defined as “events that are beyond the borrower’s control that result in a sudden, significant, and prolonged reduction in income or a catastrophic increase in financial obligations.” These include:
There’s one last alternative if waiting isn’t your thing–you can obtain seller financing, essentially bypassing the traditional mortgage. If both parties are amenable, you can enter into a lease with an option to buy, or take a mortgage directly from the seller. You’ll most likely have to show some hefty reserve funds, but if you’ve turned around your financial situation quickly after your foreclosure, it’s worth a shot to deal directly with the seller.
Keep in mind that sellers may be motivated to agree to this if they need to sell and the potential buyers they’ve met with can’t obtain a conventional mortgage–perhaps because they’ve been through foreclosures, too.
Tip: Try a mortgage broker, who can work with a variety of lenders to find you a loan. When you work directly with a retail lender, like a bank, they have a limited pool of loans to offer you. But a good mortgage broker–one with a vast network of lenders has many options, and may be able to find a mortgage solution if the foreclosure in your past is creating challenges in obtaining one.
If you stay disciplined and positive, the American dream–obtaining a mortgage and owning a home of your own–can, indeed, be yours again. Even after foreclosure.
Barbara Eisner Bayer has written about mortgages and personal finance for the past 16 years for the Motley Fool, the Daily Plan-It, and Nursevillage.com, and has been the Managing Editor for CompleteGrowth.com, Mortgageloan.com, and Credit-land.com. She’s grateful that she now knows where to turn if she ever struggles to meet her mortgage payment.
Some great new clients of mine are having a yard sale/moving sale this weekend in Holden. Here are some items that they would like to find new homes for at a reasonable price. If interested – call Jen and Dan at 508-847-3178.
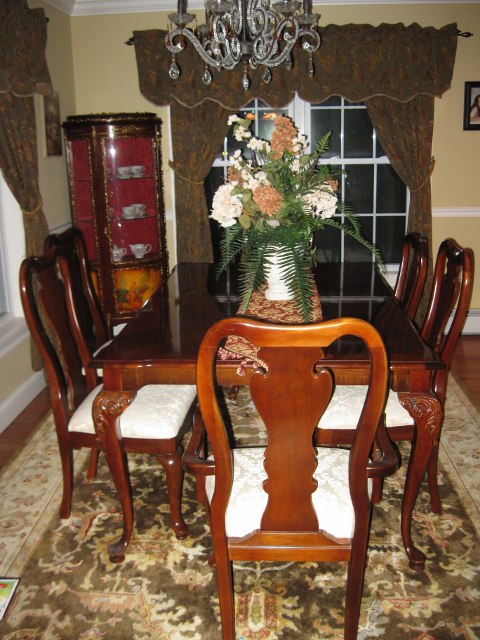

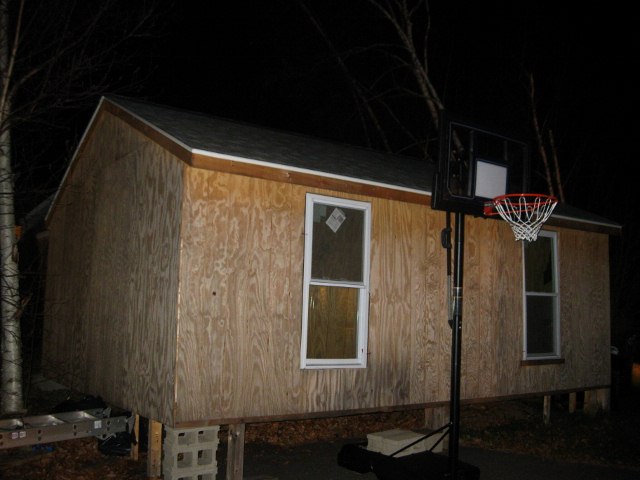

Come see this amazing house in a very desirable location on the Marlborough/Sudbury line. It’s at the end of the cul-de-sac which means you can enjoy the benefit of the neighborhood while still having your privacy. The lot is nearly twice the size of the rest with trees and no traffic (imagine!).
The house has great flow with high ceilings, 10 rooms and 4 bedrooms. The basement is nearly finished with full sized windows for daylight and plumbed for a second kitchen (use your creativity and imagination – this space can be anything from an in-law to the best game room/man town in the area).
Master bedroom has it’s own sitting room and throughout the house you’ll find small unique touches such as cut-outs and bump-outs that make this house a champion.
Stop in and see for yourself – this is not a drive-by (because you can’t).
21 Balcom Road
Marlborough
Noon to 1:30
It is For Sale By Owner but I am helping out with this open house because I live in Marlborough myself and want to see my community and neighbors succeed!
For more information, directions or to make an offer, please contact me.
Use this handy guide to figure out how quickly you can buy a home after a major financial setback when applying for a loan through FHA, Fannie Mae, or Freddie Mac.
The chart below outlines the criteria that government entities FHA, Fannie Mae, and Freddie Mac follow for major credit-busting events, including foreclosure. Although FHA, Fannie Mae, and Freddie Mac aren’t direct lenders, they wield a lot of behind-the-scenes influence by working with banks to guarantee loans and help lenders free up capital to provide more mortgages.
One of these entities may have made your loan possible without you even knowing it. Although for the most part banks make loans to whomever they want, they’ll likely find themselves following FHA, Fannie Mae, or Freddie Mac guidelines at a minimum in order to keep working with these useful partners.
Some lenders may have more stringent policies and others, willing to take greater risks, may work outside these entities and offer more liberal lending policies.
This chart offers summaries of what can be complex rules and regulations. So:
1. Look to professionals, such as a bankruptcy lawyer and a CPA specializing in bankruptcy provisions, before making major financial decisions.
2. For HUD-approved counselors, go to http://www.hud.gov/offices/hsg/sfh/hcc/fc/index.cfm. You can also call 1-888-995-HOPE for help from the Homeownership Preservation Foundation.
3. Understand what “extenuating circumstances” means in each case:
FHA: An event that was out of the borrower’s control that made a significant impact on the borrower’s finances and led to bankruptcy or foreclosure.
Fannie Mae: A nonrecurring event that’s beyond the borrower’s control that results in a sudden, significant, and prolonged reduction in income or a catastrophic increase in financial obligations.
Freddie Mac: A nonrecurring or isolated circumstance, or set of circumstances, that was beyond the borrower’s control and that significantly reduced income and/or increased expenses and rendered the borrower unable to repay obligations as agreed, resulting in significant adverse or derogatory credit information.
| FHA | Fannie Mae | Freddie Mac | |
| Foreclosure | •3-year wait. •Reduced wait if borrower has re-established good credit and can show extenuating circumstances. |
•7-year wait from the completed foreclosure sale date. •3-year wait if borrower can show extenuating circumstances (additional underwriting requirements apply for 4 years after 3-year waiting period). •7-year wait for a second home, investment opportunity, or cash-out refinancing. |
•5-year wait from the completed foreclosure sale date. •3-year wait if borrower can show extenuating circumstances. |
| Short Sale | •No wait if not in default. •3-year wait if in default at closing of short sale. •Reduced wait if borrower has re-established good credit and can show extenuating circumstances. |
•2-year wait if the borrower puts 20% or more down. •4-year wait if the borrower puts 10-20% down. •7-year wait if the borrower puts less than 10% down. •2-year wait time if borrower can show extenuating circumstances and puts 10% or more down. |
•4-year wait. •2-year wait if borrower can show extenuating circumstances. |
| Deed in lieu of foreclosure | •Same as FHA’s foreclosure policy. | •Same as Fannie’s short sale policy. | •Same as Freddie’s short sale policy. |
| Bankruptcy | Chapter 7 (liquidation): •2-year wait from the discharge date of the bankruptcy. •1-2 year wait if borrower can show extenuating circumstances. Chapter 13 (repayment plan): |
Chapter 7 or Chapter 11 (reorganization, usually involving corporations or partnerships): •4-year wait from the discharge or dismissal date of the bankruptcy. •2-year wait from the discharge or dismissal date may be accepted if borrower can show extenuating circumstances. Chapter 13: Multiple bankruptcies: |
Chapter 7 or Chapter 11: •Same as Fannie’s bankruptcy policy. Chapter 13: Multiple bankruptcies: |
Source: FHA Handbook, Fannie Mae Selling Guide, Freddie Mac Selling Guide
Please note that in most cases a short Sale is better than a foreclosure. If you or someone you know (a friend or family member) is currently faced with this situation, urge them to find out what their options are. RE/MAX Professional Associates has a short sale team that is ready to review their situation and help. Call (508-784-0504) or email me (amymullen@remax.net) to find out more information.
 In this current environment, you know someone who is considering a short-sale or is facing foreclosure. You don’t have to go the full seven degrees of separation to find them either. It’s worth the time to explore all the options available before considering foreclosure. If your friend / family member has already started the foreclosure process, there is still time to act to avoid it. RE/MAX Professional Associates has a short-sale team that is ready to help your friend or family member. Email or call me to find out more information and schedule a free consultation. Urge your friend or family member to find out their options by sending them this blog because the foreclosure process will not just go away.
Here are the facts about short sales and how to get started.
Although short sales are not hassle-free, at least you’ve got the government backing you. The Home Affordable Foreclosure Alternatives (HAFA) program provides financial incentives for lenders and borrowers to avoid foreclosure through short sales or deeds in lieu of foreclosures.
Participation in the HAFA program requires adherence to guidelines–including a standard process and minimum timeframes–that speed the process, says Dallas-based REALTOR® Tom Branch, co-author of Avoiding Foreclosure: The Field Guide to Short Sales. The HAFA program is for homeowners who can’t keep their homes with the help of a loan modification.
A short sale can be a time-consuming process, but if you can avoid foreclosure, it’s worth it in the long run.
I really enjoyed this post that was on MSN Real Estate. It captures what so many home buyers and apartment hunters face every day while they are looking at their next new possible home. Sometimes they can be funny – but not when you’ve spent the time to make the appointment and view the home. Want to have some fun with it though? Go here and do some random searches to see how many of these buzzwords you can find. Check out the pictures and see if they relate to the article.
 Nothing is ever what it seems, especially real estate.
Chances are that anyone who has looked to rent an apartment or buy a home has at some point been disappointed to find that the property barely resembled what was advertised in the real-estate listing. Perhaps the third bedroom turned out to be a closet or the kitchen that was supposed to be fit for a gourmet chef barely fit a microwave and a fold-up chair.
While real-estate agents may not like to admit it, much of this stems from their deliberate attempt to put a positive spin on the property in real-estate listings, even if that means stretching the truth.
“It’s a numbers game. For those who do it, the goal is to get people to the property and hope they’ll buy it,” says Paul Campano, senior sales associate at Keller Williams Realty in Massachusetts.
As Campano acknowledges, however, he’s unsure how sound the logic behind this method is because prospective tenants will likely just see the place and walk away.
“I’d much rather underpromise and overdeliver,” he says.
As it turns out, there is another big motivation that drives agents to put out dubious listings.
“You have to keep in mind that the agents report to the homeowner or the landlord,” says Tara-Nicholle Nelson, consumer educator for Trulia.com, an online real-estate search engine, and a former real-estate agent herself. “These days, they audit all of the agent’s online marketing, and they want to make sure that the agent is doing their job to market the home in its very best light. So the agent, in turn, is also concerned that they are marketing the property well enough for their client.”
The result is a slew of real-estate listings that exaggerate the good parts of a property and either omit the flaws or couch them in buzzwords and phrases that might have multiple misleading meanings. And according to those familiar with the real-estate industry, these sorts of deceptive listings have become more common during these difficult economic times as agents and landlords have grown more desperate to attract buyers.
We spoke with several real-estate experts to find out the real meaning behind these buzzwords and phrases so that you know what to look out for and how to read between the lines of a listing.
It may seem like a harmless word, but it spells trouble when used as an adjective in a real-estate listing, says Paul Campano of Keller Williams Realty.
“Cozy is always a potentially dangerous word. It’s really not describing any physical characteristic. Instead, it’s likely a signal of a very tight space,” he says.
So, for example, if you see the word “cozy” next to bedroom, Campano says it probably means it’s time to consider a twin or full-size bed, rather than something larger.
Other buzzwords that tend to mean the same thing include “cottage” and “intimate.”
Every home and apartment needs some fixing up after it has been lived in for a while, but the question is how much.
“My general rule of thumb is that homes are generally in a little worse condition than the listing’s language would indicate,” says Tara-Nicholle Nelson of Trulia.com. “If it says it needs TLC, it’s probably more of a handyman’s special; if it says it’s a handyman’s special, it probably needs contractor work. And when agents express in a listing that a home needs a whole lot of work, then it probably needs a whole lot of work.”
Moreover, as Nelson points out, buyers and renters should never expect that a property that “needs some work” requires only a small touch-up job.
“If that’s all it needed, a lot of homeowners and agents would do that themselves to make the property more competitive on the market,” she says.
On the other hand, many listings will highlight just how much work has been done to fix up a place over the years, using buzzwords such as “modern,” “updated” and “remodeled.” It’s important to put these words into perspective.
“People take a lot of liberty with the degree of renovation they’ve done,” says Paul Campano of Keller Williams Realty. “I guess when you’re talking about homes that are 100 years old, a kitchen renovated in the 1970s is modern by comparison, but I think that word lends itself to a great degree of interpretation.”
Tara-Nicholle Nelson of Trulia.com echoes this point: “It’s very common to see these words on homes that have ’40s construction or older that were remodeled in the 1980s. But they are not really up-to-date, so you are still pretty much going to have to redo the home.”
Many people dream of living in a penthouse of their own, but just because a listing says penthouse doesn’t mean it’s exactly that, Paul Campano says.
“There are rooms where, yes, it’s the top unit, so it’s technically a penthouse, but the room itself has no view,” he says. “So it’s a very grandiose way to describe what is just the top floor.”
In this sense, it’s not untrue, but rather misleading.
Similarly, apartment hunters should be wary when they see the phrase “tree-top view” in a listing.
“If the apartment is on a high floor or has a great view, the listing will mention it,” says Diane Saatchi, senior vice president with Saunders & Associates Realty in Bridgehampton, N.Y. “But a tree-top view usually means you have a view from the second or third floor, which could be nicer than looking at a shaft, but what you want is to be above the trees.”
Anyone who has ever looked for real estate in New York City is likely familiar with the phrase “steps from…” as in, this apartment is “steps from Columbia University” when it is really 70 blocks away in Washington Heights. The same is true in other cities and locations.
“Neighborhood proximity is a big red flag,” says Paul Campano, who markets real estate in Boston. “I’ve seen places listed as being in Davis Square because it’s become a very trendy place. And yeah, they’re close, if you consider a mile and a half close.”
When in doubt, the best thing to do is get the address of the property in question and plug it into an online mapping service to find out exactly where it is and what is nearby.
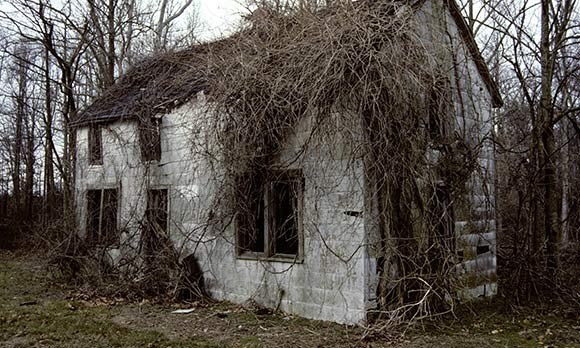 ‘Charming’
It’s a nice word, but according to Diane Saatchi, senior vice president with Saunders & Associates Realty, it usually means only one thing: The house is old. Very old.
Who doesn’t want a bit of peacefulness in their home? Unfortunately, even tranquility comes with a downside.
“Tranquil may mean that it’s just not near anything that you care about, that it’s kind of far away from any amenities or public transportation and stuff like that,” Tara-Nicholle Nelson says. By the same token, when a listing says the property is in a “convenient” location, that may mean it’s too close to those things and therefore too noisy.
Nelson says, however, that this is one example where buyers and renters have to exercise some common sense.
“I’ve worked with people who want a quiet place that takes them only 10 minutes to get to work,” she says. “But you can’t have it both ways. There are definitely trade-offs.”
Real-estate listings are often full of jargon and abbreviations, but one that should cause house hunters to think twice is FSBO, meaning for sale by owner.
“People tend to think there’s an opportunity to save money because there’s no agent involved, but actually FSBO should be a little bit of a red flag,” Trulia.com’s Tara-Nicholle Nelson says. That’s because homeowners looking to sell their property often have “very unrealistic expectations about pricing and other things.” These expectations are usually tempered by the real-estate agent working with them, but without an agent there, you may have to deal directly with the owner’s outsized expectations.
Ultimately, the biggest red flags in real-estate listings may be the descriptions that the seller leaves out.
“If it’s better for a home to be downtown and the listing doesn’t say that, then you know the home is far away from there,” says Diane Saatchi of Saunders & Associates Realty. “If a house doesn’t have much light, then the listing won’t mention light-filled rooms. And if the property is on the ground floor, the listing probably won’t mention it.”
Aside from the misleading words, it’s also important to be mindful of the potentially misleading photographs that accompany real-estate listings.
“Photographs can be very deceiving. There are wide-angle lenses that can make spaces seem bigger than they are,” Paul Campano says.
On top of that, he notes there are “virtual staging” companies that will “virtually impose furniture into a photo of the space,” in order to make it look more filled-in, even if those pieces of furniture might not fit into the room in real life.
Looking for your next great home? Go here!
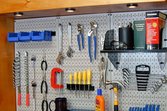 Versatile pegboard provides easy and inexpensive storage solutions for virtually any room and under-utilized wall space.
Pegboard comes as either tempered hardboard panels or metal sheets.
Hardboard panels are ¼-inch thick and feature ¼-inch diameter holes, evenly spaced 1 inch apart across the face of the entire sheet. Hardboard pegboard panels are easy to cut into custom shapes for fitting odd-shaped areas.
Hardboard pegboard comes in standard sizes (2×4-foot, 4×4-foot, and 4×8-foot sizes); commonly available colors are natural, black, and white. Latex paint color can also be rolled on.
Hardboard panels are lightweight and affordably priced; expect to pay $8 to $50 for a 4×8-foot panel.
Metal sheets come in several types of metals and weights. Some feature slots, rather than holes, to accommodate specialized accessories, such as bins and shelves. Metal pegboard sheets are durable and the perforations never lose their shape. Properly installed heavy-duty versions support up to a ton of items.
Metal pegboard sheets come in a variety of patterned and smooth finishes, and a variety of anodized colors. Standard sheet sizes are the same as hardboard, plus 16×32-inches and 4×10-foot panels. Cost: $33 to $400.
Accessories: Standardized perforations accept a wide range of hooks, clips, shelves, bins, racks, jars, and other storage accessories that you can arrange and rearrange to suit your changing needs. Use them to organize any combination of household tools, supplies and belongings. Cost: 30 cents to $15 each.


