Real Estate and *stuff *
A real person helping real people with real estate
You can scroll the shelf using ← and → keys
You can scroll the shelf using ← and → keys
 This is a great contest sponsored by HouseLogic. HouseLogic is a free site for homeowners (houselogic.com) that is full of how-to articles, Facebook links and home ownership information.
Get 6 smart tips to save big on your game-day party–and share some of your own tips for a chance to win a Super Bowl bash on us.
Have fun watching the game with friends and family while supporting a good cause–and take a tax deduction, too. Here’s what to do:
Let a brand donate their food and drink to your party. Here’s how to get involved:
Some NFL stadiums have been taking measures to go green for years now, saving hundreds of thousands in energy costs and recycling everything from straws to cooking grease. Here’s how you can conserve at home:
There are tons of blogs and websites out there that have the scoop on the latest deals at hundreds of retailers. Save big on everything from food to supplies to electronics just by spending a few minutes doing an online search. Here’s what we found:
After all, it’s the company that really makes the party special. So rather than breaking your back (and the bank) trying to get everything done by yourself, include your guests and make it fun.
Let us know some of your own great money-saving tips for hosting a Super Bowl party on Facebook—and you’ll have the chance to win a $100 gift card from HouseLogic!
No purchase necessary to enter or win. Must be a U.S. resident and 18 years of age or older at time of entry. Void where prohibited or restricted by law. Winner will be chosen at 2 p.m. Eastern time on January 31.
WOW! I am drinking my morning coffee (starting to drink my morning coffee – I measure this process in pots rather than cups) and just realized how many of my listings will be open today! This is GREAT! I am excited to be able to work with everyone so well (my sellers and the great agents at RE/MAX Professional Associates) in order to get this done all in one day!
10 Overlook Ave in Millbury – Noon to 1pm: This is a newer 3 bed, 2.5 bath colonial with MANY upgrades on a dead-end street close to the highway. You will not find this kind of square footage, at this price, in new construction but it’s so young it might as well be new construction. http://272oakstreet.epropertysites.com/
272 Oak Street Shrewsbury – 2pm to 3pm: An amazing home with unique flair and unmatched grace and elegance. 5 bed and 3 baths with 11 rooms total that includes an in-law apartment. Great neighborhood and great price! http://10overlookave.epropertysites.com/
21 Balcolm Road Marlborough – 11am to Noon: Incredible young colonial at the end of a cul-de-sac on the Marlborough/Sudbury line. This IS a stately home that can rival any other property in the area in extras, square footage, location and price. http://21balcolmroad.epropertysites.com/
28 Adams Street Worcester School House Lofts – 1pm to 4pm: NINE loft condos are available ranging from studios to 2 bedrooms in the Adams Street Lofts. Each one unique and each one incredible! High vaulted ceilings, central air, two parking spaces and more! Right off of Shrewsbury street – these are a must-see for condo shoppers. http://28adamsstreetunit208.epropertysites.com/
Get out and stop in at one of these fantastic properties before the snow flies (again) this week and DRIVE SAFE!
 If you have tried every avenue and are still in a foreclosure situation, come out of it the best way you can. Make sure that you have the right team in place to minimize your loses and help pave the way for your future. It doesn’t benefit you to “just let it happen” – take control and make it work for you. That starts with knowing which experts provide foreclosure help–often at no cost to you–and how to find them.
Your first step to get foreclosure help should be contacting a foreclosure counseling agency approved by the U.S. Department of Housing and Urban Development.
“A foreclosure counselor should help you evaluate your current financial situation by looking at your bank statements, tax returns, and monthly expenses and income,” says Kimberly Allman, manager of homeownership preservation at the New York Mortgage Coalition in New York City. A foreclosure counselor also can help you understand the programs available through banks and government agencies and serve as an advocate to help you communicate with your bank.
And don’t worry about money–foreclosure counselors provide foreclosure help for free. Find one at NeighborWorks America or by calling HUD’s foreclosure counseling hotline at 800-569-4287 or its foreclosure prevention hotline at 888-995-HOPE (4673).
A REALTOR® can help you find out if a short sale, rather than a foreclosure, is the right path for you. Use this pro to discover if you can sell your house, how quickly, and at what price. In most cases a short sale is possible! RE/MAX Professional Associates has a short sale team that is ready to move on your home because time is of the essence in this situation. The sooner you get us started on this – the sooner you are in a more comfortable situation with less stress (and less phone calls from creditors).
If a short sale seems right for you, make sure your agent is experienced with these. If not, ask for a recommendation for one who is. Short sales are tough to navigate, and they’re further complicated by your loan type–FHA vs. Veterans Administration vs. conventional loans. Real estate agents who specialize in short sales will know the proper steps and order of the steps involved. They’ll also be able to navigate the many parties involved in the process and over-burdened loss mitigation departments.
Look especially for agents who have the Short Sales and Foreclosure Resource (SFR) Certification, which requires specialized training.
You’ll need a tax expert for foreclosure help if you do a short sale or deed in lieu of foreclosure. Consult with a qualified tax adviser since forgiven debt may be taxable income, says Nancy Polomis, chair of the real estate development department at the law firm of Hellmuth & Johnson in Eden Prairie, Minn. You’ll face myriad other foreclosure-related tax issues as well, which require professional advice.
Tax advisers’ hourly rates range from $150 to $250, depending on where you live. A good choice is a certified public accountant. Check with your local CPA society to see if its members offer free advice at volunteer events like those sponsored by the Illinois CPA Society. Find a list of state CPA associations at TaxSites.
Another qualified tax adviser is an enrolled agent. EAs, like CPAs, are licensed to represent clients at an IRS hearing. Find an EA at the National Association of Enrolled Agents.
If you’re having trouble getting a loan modification, a credit counselor can give you some foreclosure help. According to the National Foundation for Credit Counseling, a counselor can advise you on managing your money and help you develop a plan to help you avoid future financial difficulties. “Often people need credit counseling because the one thing that’s holding them back from getting an affordable loan modification is high credit card payments,” says Allman. Even if foreclosure is inevitable, credit score repair can help you get back into a home sooner.
Allman often refers foreclosure clients to the nonprofit Greenpath Debt Solutions, which operates in many states. You can find a list of government-approved credit counselors from the U.S. Trustee Program.
Once your lender has filed a foreclosure lawsuit, contact an attorney. A lawyer can review the lender’s foreclosure papers to determine if it actually owns your mortgage or whether your loan servicer has made mistakes in applying your payments or assessing fees, says Lisa A. Magill, an attorney at Becker & Poliakoff in Fort Lauderdale, Fla.
You may be able to avoid foreclosure, or even a short sale, if you just have more time to sell your home, acquire secondary financing, or get a new job. For example, a lawyer can usually make arrangements with the lender to give you more time by filing responses and motions in the lawsuit, says Magill.
Also consider consulting a bankruptcy attorney, who can help you discover whether bankruptcy is a viable option for avoiding foreclosure, says Polomis.
Lawyers charge $150 to $300 per hour or a flat fee of $1,000 to $2,500 to defend a foreclosure action or file a bankruptcy petition. Contact your local legal aid office, such as the Mid-Minnesota Legal Assistance, or your local bar association, like the Florida Bar, for a list of agencies that offer free legal representation. A list of state resources may be found at the National Legal Aid and Defender Association.
Before making your decision to short sale or foreclose – give me a call. We can work through this together and find the right course of action for you. Not every person and situation is the same and I’m ready to find out what is going to the best for you.
 It’s been an exciting week! I listed two new houses this week and have been discussing this topic so much that I thought it was time to make a post. It’s a fine line to walk when you are both living in your home and showing it to potential buyers. You don’t want to feel like you are living in a hotel but at the same time would like to ensure a quick home sale. There are a few things you can do to help the process and still maintain your life style In general, make your home warm and inviting to boost your home’s value and speed up the sale process.
Before you can worry about where to place furniture and which wall hanging should go where, each room in your home must be spotless. Do a thorough cleaning right down to the nitpicky details like wiping down light switch covers. Deep clean and deodorize carpets and window coverings.
It’s harder for buyers to picture themselves in your home when they’re looking at your family photos, collectibles, and knickknacks. Pack up all your personal decorations. However, don’t make spaces like mantles and coffee and end tables barren. Leave three items of varying heights on each surface, suggests Barb Schwarz of www.StagedHomes.com in Concord, Pa. For example, place a lamp, a small plant, and a book on an end table.
When a room is packed with furniture, it looks smaller, which will make buyers think your home is less valuable than it is. Make sure buyers appreciate the size of each room by removing one or two pieces of furniture. If you have an eat-in dining area, using a small table and chair set makes the area seem bigger.
Highlight the flow of your rooms by arranging the furniture to guide buyers from one room to another. In each room, create a focal point on the farthest wall from the doorway and arrange the other pieces of furniture in a triangle around the focal point, advises Schwarz. In the bedroom, the bed should be the focal point. In the living room, it may be the fireplace, and your couch and sofa can form the triangle in front of it.
Brush on a fresh coat of warm, neutral-color paint in each room. Ask your real estate agent for help choosing the right shade. Then accessorize. Adding a vibrant afghan, throw, or accent pillows for the couch will jazz up a muted living room, as will a healthy plant or a bright vase on your mantle. High-wattage bulbs in your light fixtures will also brighten up rooms and basements.
Lay logs in the fireplace, and set your dining room table with dishes and a centerpiece of fresh fruit or flowers. Create other vignettes throughout the home—such as a chess game in progress—to help buyers envision living there. Replace heavy curtains with sheer ones that let in more light.
Make your bathrooms feel luxurious by adding a new shower curtain, towels, and fancy guest soaps (after you put all your personal toiletry items are out of sight). Judiciously add subtle potpourri, scented candles, or boil water with a bit of vanilla mixed in. If you have pets, clean bedding frequently and spray an odor remover before each showing.
Mow your lawn and trim your hedges, and turn on the sprinklers for 30 minutes before showings to make your lawn sparkle. If flowers or plants don’t surround your home’s entrance, add a pot of bright flowers. Top it all off by buying a new doormat and adding a seasonal wreath to your front door.
All of this should come with a grain of salt and reasonableness. We can walk through your house and make small changes that will increase the appeal of your home while not changing your lifestyle or costing you extra money. Please give me a call if you would like to schedule an appointment to see what can be done to get your home sale ready.
In the meantime, please check out my two new listings that prompted this blog:
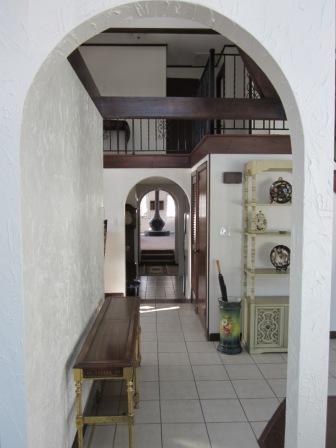 272 Oak Street in Shrewsbury – 4 bed, 2 bath, 3000 sqft, inlaw apartment – contemporary style and grace makes this home unmatched! You really have to walk through this house to appreciate it. So many updates (roof, siding, heating system, flooring, carpet) and a very aggressive sale price. http://272oakstreet.epropertysites.com/
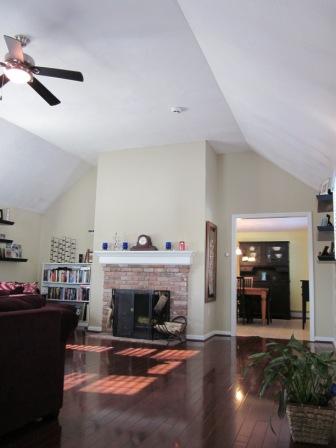 10 Overlook Ave Millbury – 3 bed, 2 bath newer home, better than new construction with the upgrades that the sellers have done such as the trex deck in back – nursery or office off the master bed that has a walk-in closet, very motivated sellers and the flat screen wall mount tv in the master bedroom stays! – http://10overlookave.epropertysites.com/
 Low-cost kitchen storage strategies bring calm to your kitchen, banishing stress-inducing clutter and leaving the space calm and orderly. Good news for budget-minded cleaning compulsive: Getting organized in the kitchen won’t drain your piggy bank! Stash more cash and control the chaos with these low-cost kitchen storage solutions, all readily available at home centers, discount stores and online.
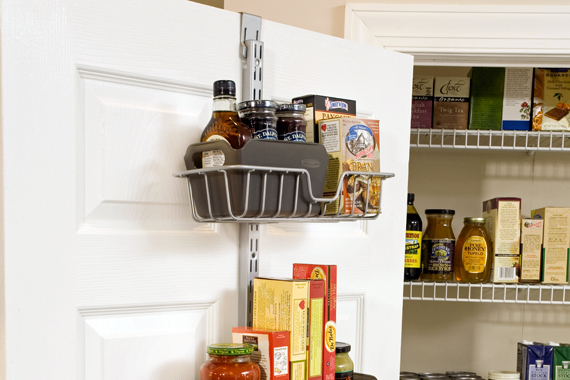 Rack attack: Store pots, everyday dishes, spices, and wine on racks that are freestanding, wall-hung, and ceiling-hung–and voila! Everything is in its own location, visible, and easily accessible!
Position the racks where they make sense: A pot rack above the cooktop; a dish rack close to the dishwasher for quick unloading; spices near the range or meal prep area; a wine rack near the wine glasses and dining table.
You’ll find racks in metal, wood, and other materials, starting as low as $10 to $15.
Shelf expression: You can size an open shelf to fit anywhere you need it and paint or stain it to match your décor. Use shelves for storing such kitchen necessities as cookbooks, attractive dishware, oils and vinegars, and spices.
Home improvement centers have storage sections where you can hunt, but don’t overlook the office supply and bathroom sections for even more low-cost shelves.
You’ll find cool shelves starting as low as $8.
 Great divide: Organize the contents of kitchen drawers and cabinets with wire or wood inserts. Drawer dividers keep utensils sorted and orderly. Vertical dividers inside cabinets create a spot for storing trays and cookie sheets. You’ll also find special inserts for storing knives and spices neatly inside drawers.
Available in wire, wood, or plastic, dividers start at about $3.
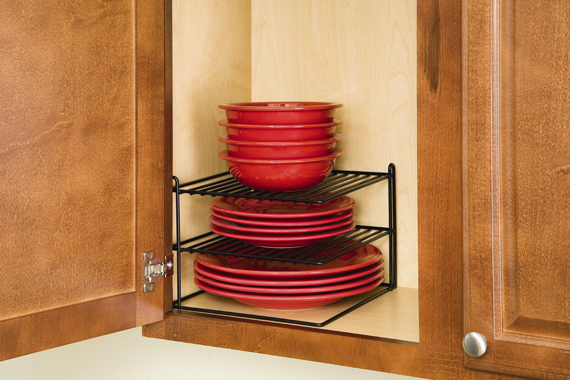 Elevated thinking: Wire stacking shelves have legs to elevate the storage surface. Set a stacking shelf on a countertop, existing shelf, or inside a cabinet to increase kitchen storage space. Use a stacking shelf for canned goods, dishware, spices, and more.
Prices start at about $6.
Hang ups: Install pegs or hooks along a backsplash, inside cabinets, or anywhere on a kitchen wall to create a place for cups, hot pads, cooking utensils, keys, and recipe clips. Hooks are available that fit over doors or come equipped with magnets that adhere to any metal surface.
Pegs and hooks start as low as $1.
Basket case: Baskets come in a variety of materials to complement your décor, from natural woven grasses to canvas to colorful plastic bins. Set baskets on open shelves, inside cupboards, and on the kitchen counter to round up small items, such as napkin rings and bamboo skewers.
Baskets are great for storing dish towels, cloth napkins, and coupons. Prices start as low as $1.
 With the storm fast approaching, I thought this would be a good topic for the blog. My first winter storm in my house I was enjoying a cup of hot steamy beverage on my couch when I heard (and felt) a large BANG on the wall behind me. The addition to my house, that I had closed off to conserve heat because it was only being used as a work room, had developed a massive ice dam – which I was unaware of. The ice dam, with the inches of snow piling up on it, slide off the roof of the single story addition and took the metal gutter with it. I then had a metal gutter blowing in the wind, banging on my house! It spared the window but damaged the side of the house, the gutter and the roof to the addition.
During the colder months, preventing ice dams should be a primary concern. Here’s how to protect your home from damage.
Over the five-year period leading up to 2007, water damage and freezing accounted for the second largest share of homeowner insurance claims, according to Claire Wilkinson of the Insurance Information Institute. The average homeowner claim for such damages was $5,531.
Ice dams are responsible for cracked plaster ceilings and walls, peeling paint, soaked carpets, and buckled wood floors. Less visible but no less destructive effects include drenched insulation, rotting joists, and the formation of mold. The most common form of ice dam-related damage is collapsed rain gutters, which can cost $100 to $300 per side to repair.
As heat rises from a home, it melts the accumulated snow on the roof. That melted snow travels down the roof in liquid form until it reaches the eave line and gutter, where it refreezes due to colder temps. This ice ridge continues to expand, blocking the flow of subsequent snow melt.
As water continues to melt higher up the roof, it collects behind the ice dam in the form of a puddle. Because that water sits over the warmer portion of the roof, it doesn’t freeze.
In order for ice dams to form, there needs to be roof snow buildup, home heat loss, and subfreezing temperatures. The more snow, the larger the heat loss, and the longer the subfreezing temperatures remain, the higher the likelihood that ice dams will materialize.
Homeowners can’t control the weather, but they can do something about heat loss. “The main goal is to keep heat from reaching the roof, thus preventing snow melt in the first place,” explains Doug Bruell, president of Cleveland’s 25-year-old North Coast Insulation. Proper insulation and ventilation of the attic space is intended to keep the roof surface at or near outdoor temperatures.
Typical steps include insulating the attic floor and installing soffit, gable and/or ridge vents to expel heat. Folding attic stairways and recessed light fixtures also need to be insulated. “All penetrations into the attic from the heated living space need to be addressed,” adds Bruell. Homeowners can expect to pay $800 to $1,500 to insulate the attic, plus another $300 to $600 for the installation of vents.
The process is a bit more involved for homes with finished attics, says Bruell. To facilitate sufficient cold air flow from soffit vent to ridge vent, baffles or tubes are installed between the ceiling insulation and the underside of the roof. This might involve opening up the ceiling.
According to the U.S. Department of Energy, adding insulation to an unheated attic will have a greater impact on energy consumption than placing it anywhere else in the house. A properly insulated and ventilated attic not only reduces winter heating bills, it will trim summer cooling bills by expelling heat buildup. You can expect to save 10% to 50% on your heating and cooling bills.
In addition, you may qualify for a federal tax credit of up to $1,500. Bruell estimates that in most cases, the procedure pays for itself in four to five years.
In theory, roof rakes, brooms, and other long-handled devices can be used to remove snow before it has a chance to melt. In practice, however, the scheme is difficult to pull off, considering that most homeowners can’t reach all areas of the roof.
Electrically-heated deicing cables, which install along eave lines to inhibit water freeze, are only moderately effective, says Bruell. “These heat cables often just back up the problem, forcing the dams to form higher up the roof.” In addition to the purchase price ($150 to $300), and installation ($300 to $500), these cables require electricity to run. They also can shorten the life of roof shingles.
Enjoy the snow everyone!
Homeowners suffering the effects of an ice dam–or those who fear a leak is imminent–can hire a roofing company to remove the ice buildup. Rather than employ hammers, chisels, and salt, which can damage the roof and gutters, technicians will steam away the ice and remove any remaining snow. Expect to pay around $500 or more for the service. It goes without saying that do-it-yourself removal can be dangerous when it involves ladders, heavy ice, and slippery roofs.
Enjoy the snow!
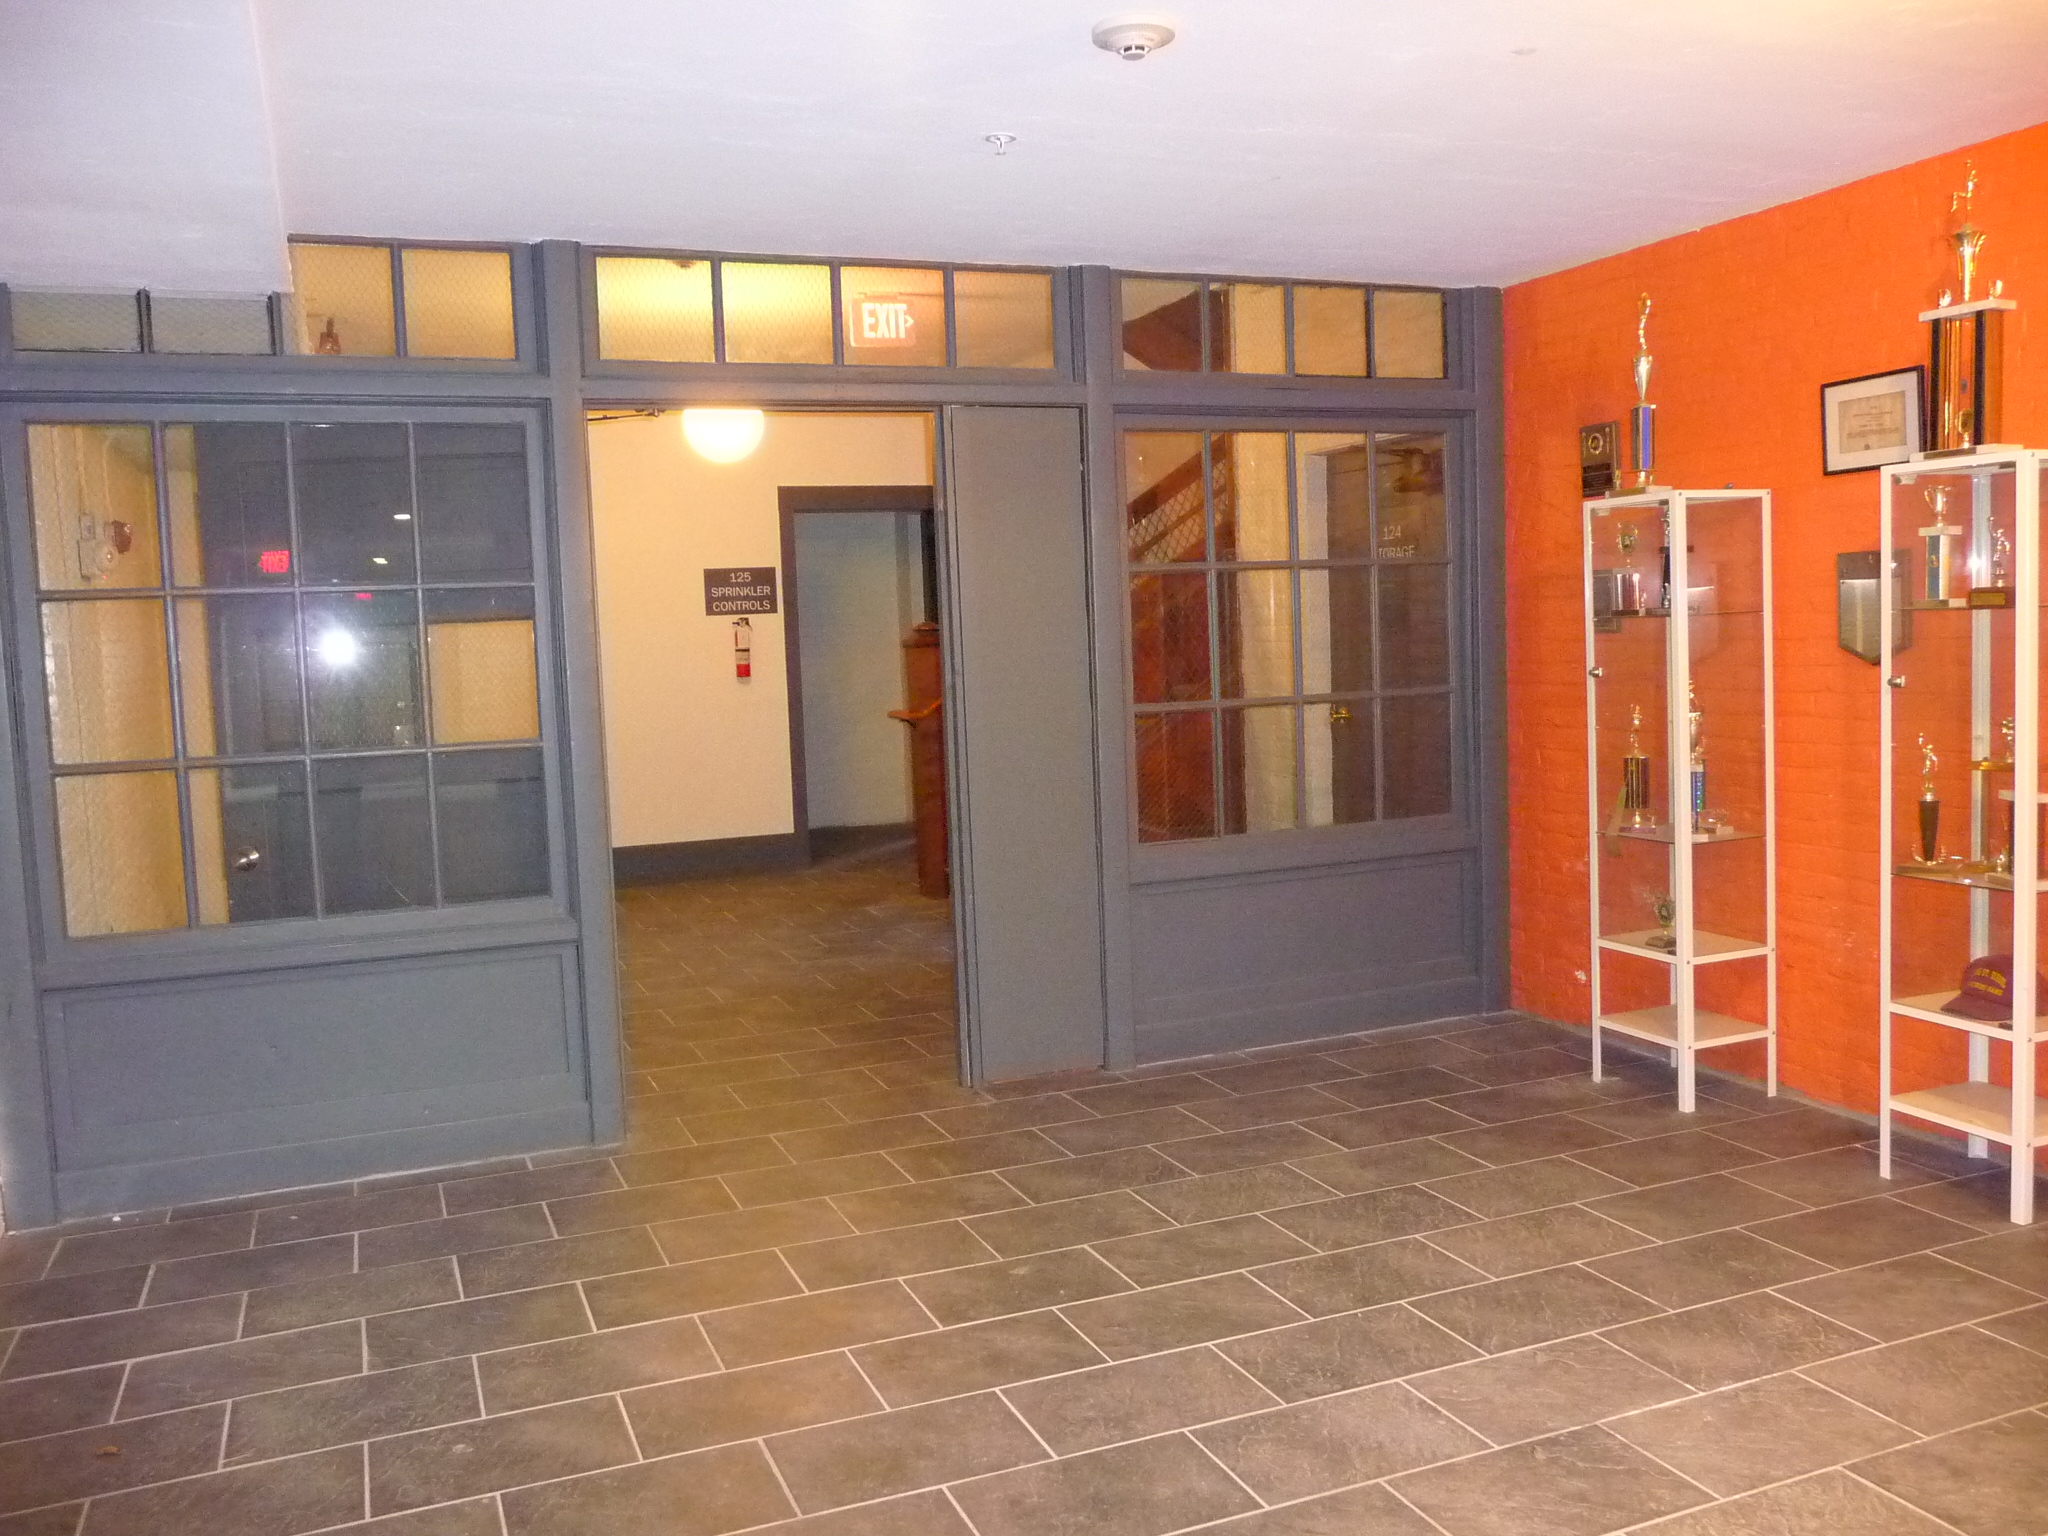 Welcome to the Adams Street School House Condos! These are beyond what you usually see in Worcester and you really HAVE to see them! Renovated from an 1894 closed school-house and having top of the line amenities but still retaining the character of the past – these are amazing!
The Adams Street School is a Classical Revival / Victorian Eclectic brick building first constructed in 1896. The interior spaces – classrooms, corridors, and stairwells – share generous ceiling heights, quality finish materials, and a durability that have served the school well throughout its lifetime. The loft-style units in the former Adams Street School cover a range of unit types and sizes, from simple studios, to 1- and 2-bedroom units, to attic lofts with cathedral ceilings and open mezzanines. The particular historical details that remain, the adapted residential layout and the varying views from the ample windows create a unique environment in each unit.
The Crawford Realty Team of RE/MAX Professional Associates is proud to offer you NINE units to choose from. We are open Sundays 1pm to 4pm so that you can stop in and take a look. Come on by and pick out your new home – and have a blast while doing it!
The School House is located right off of Shrewsbury Street so you would be close to fantastic restaurants, Union Station, I290 and I190. Pets are allowed and there is off-street parking. The units feature Energy Star appliances, granite countertops and laundry hook-ups.
Here is a quick summary of the available units:
Unit 104: 1 bed, 1 bath $109,000
Unit 105: 1 bed, 1 bath $116,700
Unit 106: 1 bed, 1 bath $139,700
Unit 108: 1 bed, 1 bath, study $198,700
Unit 206: 1 bed, 1 bath, study $190,000
Unit 208: 2 bed, 2 bath $279,700
Unit 306: 1 bed, 1 bath, study $192,700
Unit 309: 2 bed, 2 bath $192,700
Unit 310: 1 bed, 1 bath, interior loft $288,700
We are open Sundays 1pm to 4pm and Thursdays 4pm to 6pm for January and February. If you would like more information or need to schedule a different time – just let me know! I am really excited about these units and can’t wait to talk to you about them!
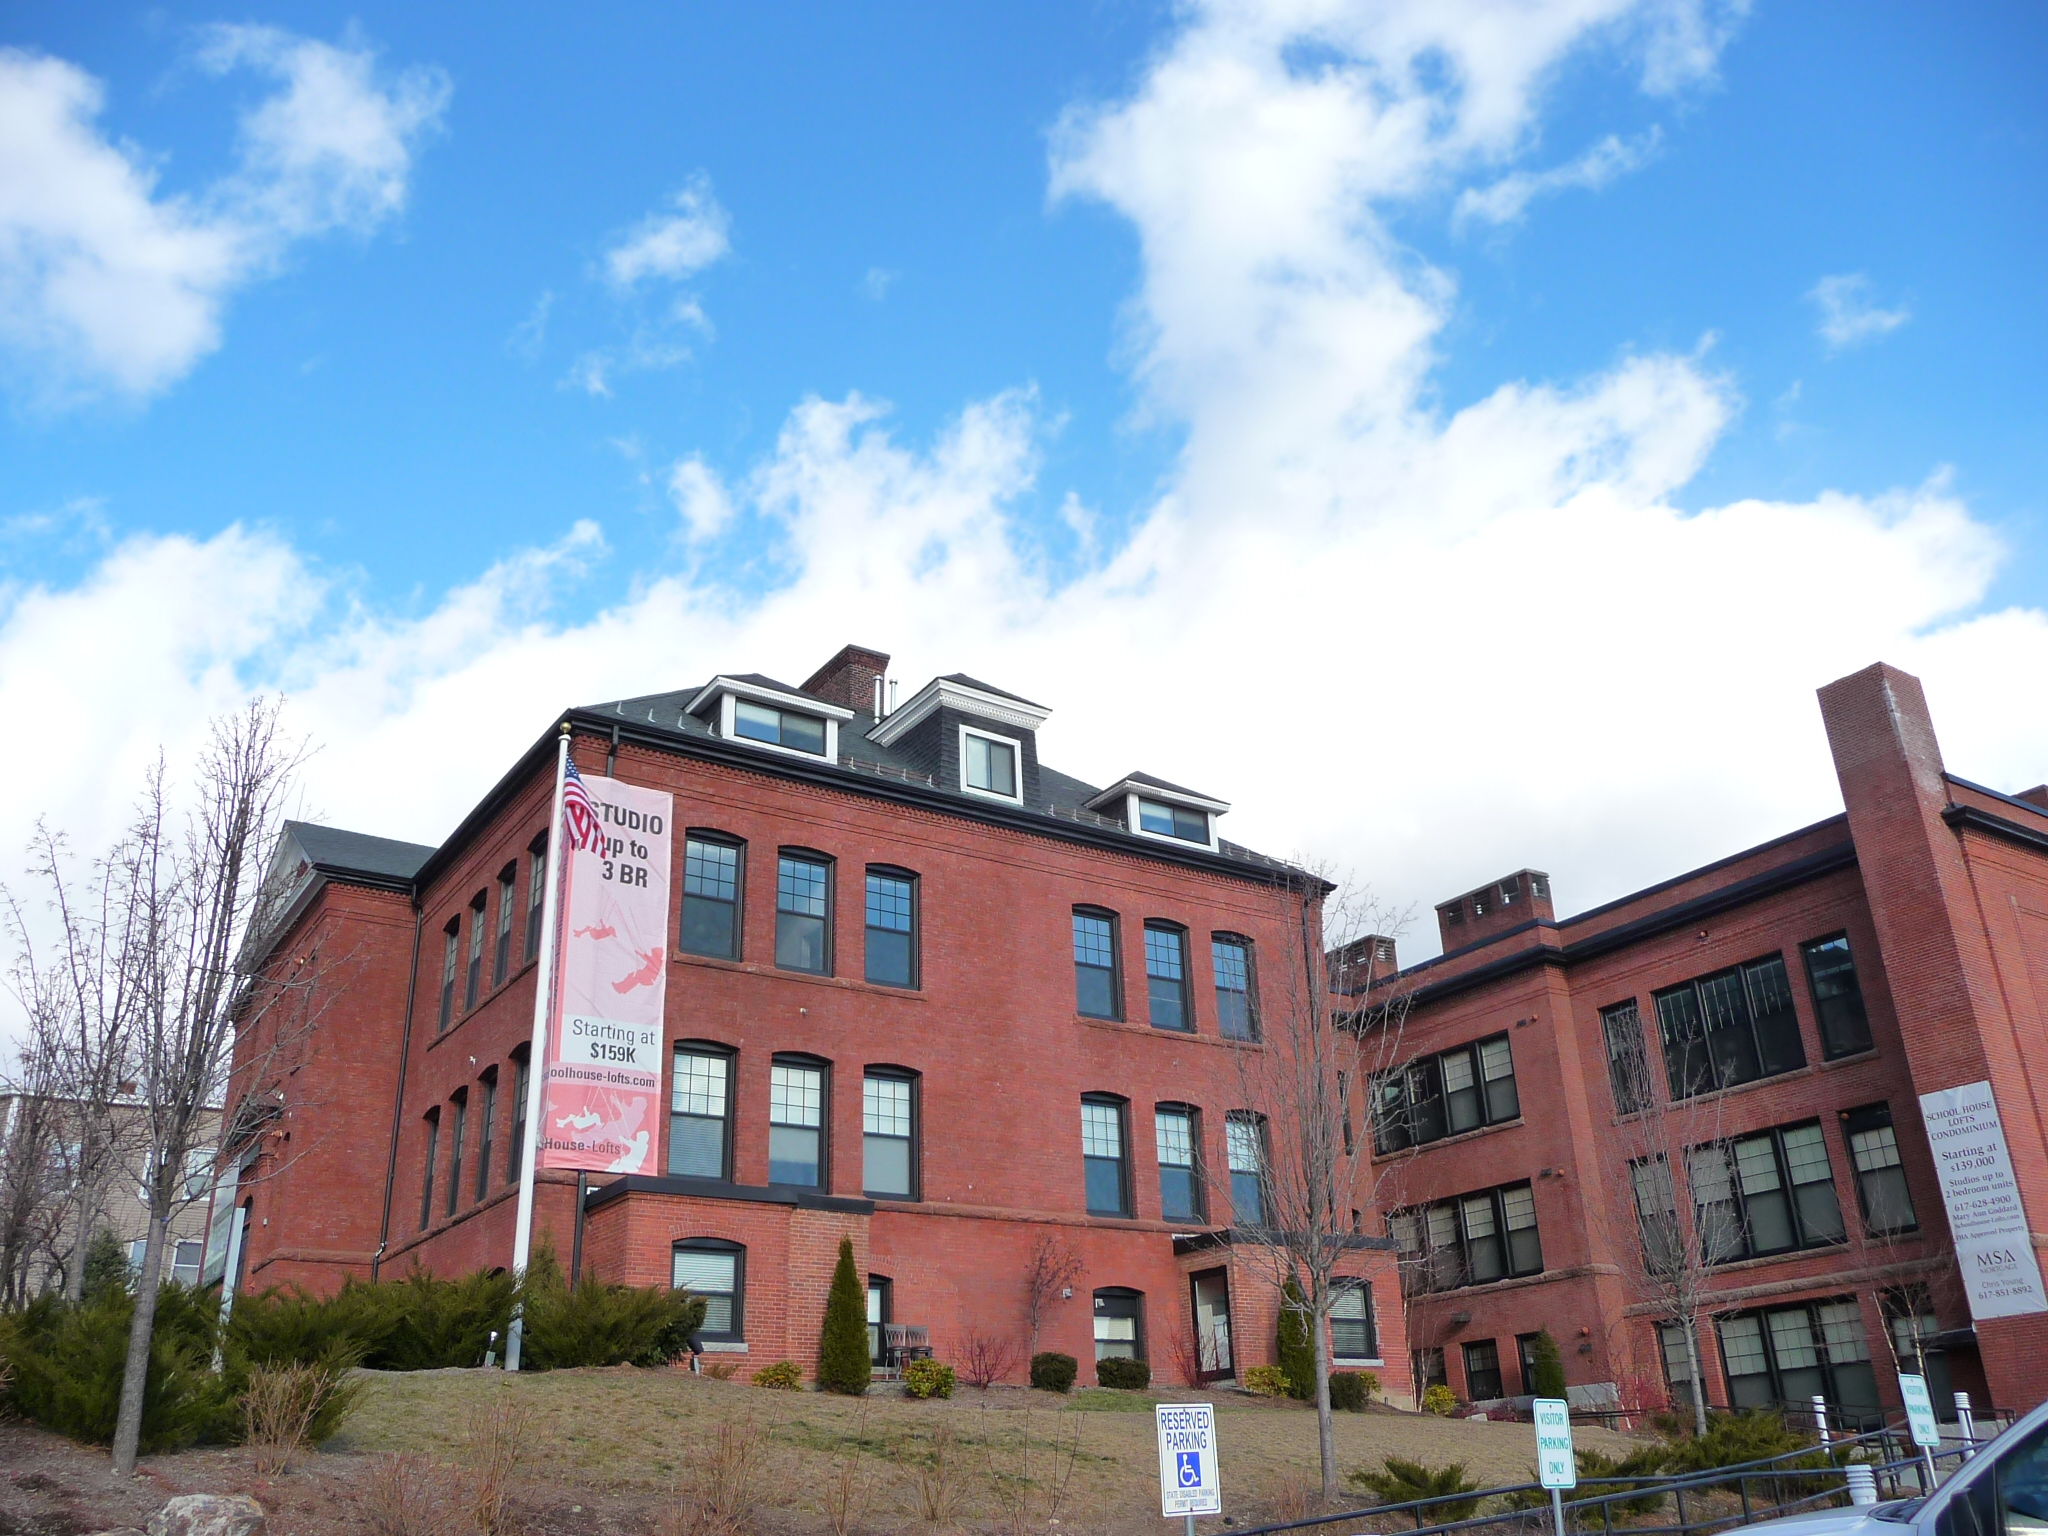


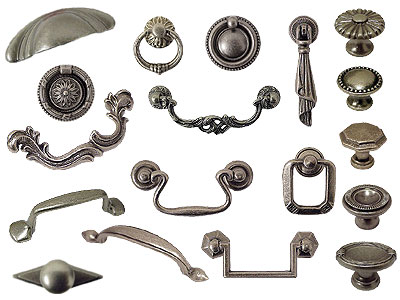 Replace old kitchen cabinet hardware and gain an instant style update that’s simple to do and easy on the budget. It’s a quick way to really make an impact on the room and express yourself. I am all about expressing my individual style and if you take a few moments in this aisle at your local Lowes, you will be amazed at all the choices you have.
Replacing kitchen cabinet hardware is a job you can do yourself. But note there’s a wide range of sizes when it comes to the spans between screws on kitchen cabinet hardware. You’re in luck if your doors feature a knob with a single screw that secures to the door or drawer front, and you want to replace it with the same.
Otherwise, you’ll need to measure precisely the spread between screws. Use a measuring tape to measure from the center of one screw hole to the center of the other. Write the measurement down and count the number of pulls and/or knobs that you need. If you’re making your purchase at a home center, bring the handle and dimensions with you.
If you opt for handles that don’t match up with existing holes, fill holes with wood filler and camouflage the repair with fresh stain or paint. Or you can cover the fix with a backplate that fits behind the new handle.
Hinges can be difficult to switch out because there are so many different types and sizes. If your kitchen cabinet hinges match the finish on the new hardware or if the hinges are hidden anyway, you can keep the originals.
Otherwise, before removing all the hinges, remove just one and then shop around—online or at a home center—to make sure you can find one that will work for your installation.
This a really fun way to the spend the afternoon! It gives a brand new look to your kitchen and it’s easy to do. We will be talking about this in up-coming events at a Lowe’s location in Worcester County – ask me more about it!
 I am not big on New Year’s Resolutions but I am big on having a plan. This is a good time of year to make a plan because the calendar is fresh and clean (and half priced if you still like to use wall calendars). Your home is probably your biggest investment. To manage it, create a financial plan that takes into account repairs, upgrades, mortgages, insurance, and taxes.
Use our home financial plan budget worksheet, and start by writing a list of expenses, such as:
With this newfound grip on your home’s expenses, you can create a home financial plan that’ll help you there for years with maximum enjoyment and minimum anxiety.
Yup, you already shell out a lot for your mortgage, but can you pay more? Even a little extra each month can add up to an earlier payoff. Let’s say you have $200,000 in outstanding principal and a 20-year fixed-rate mortgage at 5%. Your monthly payment is $1,319.91. But if you can manage to pay another $100 a month, you’ll save $14,887 in interest.
Run the numbers yourself for your home financial plan.
Advantages of an early payoff, says Alan D. Kahn, a financial planner in Syosset, N.Y.:
Of course, if you’re still saving for retirement, put the 100 bucks elsewhere:
Your vegetable garden is pointless without a fence to keep out rabbits; likewise, your home financial plan will come to nothing without an insurance “fence”:
Homeowner’s insurance. Basic coverage for your home and everything in it. The average cost is $636 per year but this varies widely by state.
Liability coverage. Protects you from a lawsuit if someone gets hurt on your property, for example. Your best bet: An umbrella policy. For about $300 a year you can by a typical $1 million policy.
Various disaster insurance policies. Optional policies cover flood, earthquake, and hurricane damage. As part of your home financial plan, you have to research to see what disaster coverage, if any, you need in your area, and what your standard policy already covers. For $540 a year you can buy flood insurance, for example.
For your basic policy, get homeowners insurance with full replacement coverage in case your house burns to the ground.
That sounds simple, but heads up on calculation. Remember that you own a house as well as the land on which it sits. So even though you bought your home for $300,000, it may cost only $100,000 to rebuild it. Your policy limits should reflect this. This difference will vary widely by region.
Another heads up: Don’t make the common and potentially disastrous mistake of thinking that because your home has fallen in value you need less insurance. If you bought a $1.2 million townhouse in Florida during the boom, it’s true it now may only sell for $600,000. But the replacement cost of the townhouse hasn’t changed much, so you can’t improve your home financial plan by cutting insurance costs that way.
Other ways to cut your insurance budget:
You own a home, so you’ll be spending money on everything from a new faucet to—surprise!—a new roof. Freddie Mac and other authorities say as part of your home financial plan, you should be prepared to spend 1% to 3% of the market value of the home annually on maintenance. To be extra-prudent, open a savings account and make regular payments until your account reaches 1% to 3% of your home’s current value.
To help you budget:
Start with the inspection report you received when you bought the house. Did the inspector indicate that you would need a new roof in five years? A new furnace in 10?
Keep a log of your major appliances’ age so you can estimate when they’ll need replacing. Some estimated life spans:
Then get estimates on what replacements will cost and start saving.
Consider ongoing non-emergency maintenance, too. Do you live in New England? Price a snow blower and get bids from plow services.
Resist the siren call of the home equity loan to take care of everything. That just defeats your efforts to pay off the mortgage early.
Separate out what you want from what you need. A $50,000 kitchen remodel is nice, but you’ll recoup only 76% of the project cost your home’s resale, according to Remodeling magazine.
If you can afford to redo, go for it. Just don’t confuse your necessary repairs (new oil furnace—about $4,000) with your discretionary upgrades (Viking range—$6,000 and up).
Even if your lender handles your property taxes from an escrow account, you need to budget for them in your home financial plan. They creep up almost every year, it seems. Take responsibility for tracking the changes in your area: Look over past tax bills to get a sense of how quickly they’ve risen in the past.
Or if your lender handles escrow and you haven’t saved your bills, ask for an accounting. The median annual property tax payment is $2,198, but that hides the enormous range in medians from state to state:
You can generally deduct property taxes on your federal return. A tax pro can tell you how much of a tax break you’ll get, to help you fine tune your home financial plan.
You may be able to reduce your tax burden by getting a reassessment. Do your homework first: Are comparable houses taxed less than yours? Ask the local assessor what formula is used to set tax rates. You can challenge the assessed value and get yourself a rollback.
A plan is exactly that – a great way to pace yourself and keep working towards your financial goals. The unexpected will always happen and with a plan you are prepared for that. Now, who is going to spend their Friday Night writing out a financial plan for their home? 🙂
 The Making Home Affordable program offers at-risk homeowners a chance to modify mortgages to avoid foreclosure on their homes. This is just one of the possible solutions that are available to home owners who are in distress or are facing that possibility.
Making Home Affordable’s modification option is known as the Home Affordable Modification Program, or HAMP. It’s designed for homeowners who are likely to lose their homes because they can’t keep up with mortgage payments. Even if you aren’t behind on payments yet, you can qualify for help if you can demonstrate that you will fall behind soon.
To qualify for HAMP, the home must be your primary residence and you must owe $729,750 or less on a first mortgage that was originated on or before Jan. 1, 2009. Your monthly payment on your first mortgage must be greater than 31% of your monthly gross income. Second mortgages and home equity lines of credit don’t count. You must also demonstrate financial hardship such as a jump in mortgage payments or a drop in income.
A loan modification makes sense if you can’t afford your current mortgage payment but could manage to stay current if that monthly payment is lowered. Second homes, which include vacation homes and rentals, don’t qualify for the program. Homes of up to four units are eligible, with higher loan limits, as long as you occupy one of the units. HAMP is scheduled to expire at the end of 2012.
HAMP begins with a trial phase. Contact your lender to initiate the process, or call 1-888-995-HOPE to get free assistance from a housing counselor approved by the U.S. Department of Housing and Urban Development. The lender will calculate a lower monthly payment, which you must make on time for at least three months. After successfully completing the trial phase, your lender should make the loan modification permanent.
While lenders may accept some undocumented information up front to begin the process, eventually you’ll need to file detailed paperwork to earn a permanent modification. It’s better to get your documentation in order in advance. HAMP administrators say the leading reason trial modifications fail to be made permanent is missing paperwork.
Start by gathering information on your income (pay stubs), expenses (mortgage statements, tax and insurance bills, debt balances), and assets (bank and non-retirement savings statements). You’ll need that information to fill out the Request for Modification and Affidavit. Also complete IRS form 4506T-EZ, which allows your lender to review your income tax returns. File a Hardship Affidavit as well. If possible, send all of the documents at once by certified mail to your lender to lessen the likelihood of lost paperwork and delays, says Nicole Hall, editor of LendingTree.com.
A lender can modify a mortgage in several ways: lower your interest rate, reduce your principal, or extend the term of the loan. The basic goal is to use one or more of these approaches to get your monthly mortgage payment, including real estate taxes and homeowners insurance premiums, down to a more affordable 31% or less of gross (pre-tax) income. Lenders are allowed to cut your interest rate to as low as 2%, if necessary. The average HAMP modification has reduced monthly payments by $640.
To get a ballpark figure of how much a modification might lower you monthly payment, run the numbers for yourself. If, for example, your current mortgage payment is $2,000 and your monthly gross income is $4,000, then you’re paying 50% of your pre-tax income toward the home loan. A typical modification to bring that figure down to 31% would reduce the payment to $1,240, a savings of $760 a month.
Even if you’re facing foreclosure, HAMP is worth a shot. The foreclosure process is suspended while you’re in the trial phase of the modification. Foreclosure can be avoided altogether if you can demonstrate the ability to keep up with the new, lower payment and graduate to a permanent modification. Keep in mind that the foreclosure process can resume if you miss payments during the trial phase or fail to get approved for a permanent modification.
Some owners won’t be able to stay in their homes, even with a mortgage modification. To avoid foreclosure, look into the federal Home Affordable Foreclosure Alternatives program. HAFA offers lenders financial incentives to opt for a short sale or deed-in-lieu rather than a foreclosure. Although the program doesn’t officially go into effect until April 5, 2010, some lenders may initiate it early.
In a short sale, a borrower sells a home for less than the outstanding mortgage, and the lender takes the proceeds and considers the debt paid off. In a deed-in-lieu, the homeowner turns over the home to the lender, and the mortgage is closed. Although neither option is ideal, either can make sense if a loan modification isn’t attainable or sufficient.
To learn more about this option and to see what other options might be available to you, give me a call. RE/MAX Professional Associates recognizes the need for this type of information and already has a team ready to help you.

