Real Estate and *stuff *
A real person helping real people with real estate
You can scroll the shelf using ← and → keys
You can scroll the shelf using ← and → keys
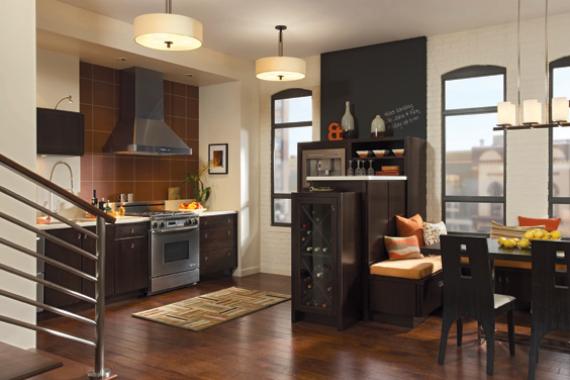 It’s not a secret that a kitchen can make or break a house sale. It’s the room we spend the most time in and it’s the room that most buyers give the highest priority. Even if you are not considering selling your house – we still all focus on the kitchen.
I thought this would be a great blog to go with our in-store demo at Lowe’s this evening. We will talking with the experts in kitchen cabinetry at Lowe’s in Ware (http://www.meetup.com/Lowes-Home-Improvement-In-Store-Demos/events/16642827/) as part of our weekly series. Stop in the find out more about your kitchen cabinet choices, costs and where to begin when planning your kitchen remodel.
This article keeps it simple – Keep the same footprint, add storage, and design adequate lighting so you preserve value and keep costs on track.
Simple enough? Not so fast. The National Kitchen and Bath Association (NKBA) recommends spending at least six months planning before beginning the work. That way, you can thoroughly evaluate your priorities and won’t be tempted to change your mind during construction. Contractors often have clauses in their contracts that specify additional costs for amendments to original plans. Planning points to consider include:
Because planning a kitchen is complex, consider hiring a professional designer. A pro can help make style decisions and foresee potential problems, so you can avoid costly mistakes. In addition, a pro makes sure contractors and installers are sequenced properly so that workflow is cost-effective. Expect fees around $50 to $150 per hour, or 5% to 15% of the total cost of the project.
No matter the size and scope of your planned kitchen, you can save major expense by not rearranging walls, and by locating any new plumbing fixtures near existing plumbing pipes. Not only will you save on demolition and reconstruction, you’ll greatly reduce the amount of dust and debris your project generates.
A six-burner commercial-grade range and luxury-brand refrigerator might make eye-catching centerpieces, but be sure they fit your lifestyle, says Molly Erin McCabe, owner of A Kitchen That Works design firm in Bainbridge Island, Wash. “It’s probably the part of a kitchen project where people tend to overspend the most.”
The high price is only worth the investment if you’re an exceptional cook. Otherwise, save thousands with trusted brands that receive high marks at consumer review websites, like www.ePinions.com and www.amazon.com, and resources such as Consumer Reports.
Some guidelines:
“People are putting more emphasis on functionality and durability in the kitchen,” says McCabe. That may mean resisting bargain prices and focusing on products that combine low-maintenance with long warranty periods. “Solid-surface countertops [Corian, Silestone] are a perfect example,” adds McCabe. “They may cost a little more, but they’re going to look as good in 10 years as they did the day they were installed.”
If you’re not planning to stay in your house that long, products with substantial warranties can become a selling point. “Individual upgrades don’t necessarily give you a 100% return,” says Frank Gregoire, a real estate appraiser in St. Petersburg, Fla. “But they can give you an edge when it comes time to market your home for sale” if other for-sale homes have similar features.
To add storage without bumping out walls:
Having a good rapport with your project manager or construction team is essential for staying on budget. “Poor communication is a leading cause of kitchen projects going sour,” says McCabe. To keep the sweetness in your project:
Consumers spend more money on kitchen remodeling than any other home improvement project, according to the Home Improvement Research Institute, and with good reason. They’re the hub of home life, and a source of pride. With a little strategizing, you can ensure your new kitchen gives you years of satisfaction.
Please stop in at Lowe’s at 6pm and join us for an in-person discussion. For more information: http://www.meetup.com/Lowes-Home-Improvement-In-Store-Demos/events/16642827/.
 The spring market is upon us! It seems a tad early this year but with all the news articles about rising interest rates many buyers are making their choices now instead of waiting. As a seller or soon-to-be-seller, don’t wait! Get your home ready and on the market now to take full advantage of this early market.
This is the first in a small series of articles to help you get your home “sale ready”. The kitchen is often the first room that a buyer will go to during a viewing and is vitally important to the overall impression of your home.
You can repair kitchen counter mishaps with only a little time and money. Big boo-boos, however, will need professional help.
Even granite counters suffer kitchen wear and tear. But you can make them shine with a little time and know-how. After you fix them, don’t forget to reseal them.
Cracks, chips, scratches: Fill nicks in granite by building up layers of epoxy resin colored to match the stone. Clean the area first with acetone, which breaks down grease. Be sure to open a window for ventilation.
Stains: The type of stain–wine or ink, oil or bleach–determines the type of poultice you’ll need to suck it out. A paste of flour and hydrogen peroxide pulls out grease, oil, bleach, and ink stains; a mix of flour and bleach cleans wine stains. If you want to go commercial, check out Alpha, Aqua Mix, and StoneTech stone cleaners. Cost: $6 to $20.
Solid surface countertops, such as Corian, are man-made from resin, acrylic, and other materials. They’re tough but not impervious to scratches and stains. To repair minor scratches, rub a white polishing compound on the area with a wool pad, then apply a countertop wax.
For deeper scratches or cuts, call a professional. Figure labor costs at about $15 to $35 an hour. If you need to replace portions of the counter, figure at least $35 to $65 per square foot.
Fixing gouges or covering burns in laminate is tough for mortals, though repairing minor problems is doable.
Bigger problems will require replacing the damaged stretch. Laminate comes in a billion colors, but finding an exact match for an old counter could be difficult.
To get the look you want, replace the counter. Labor will cost $15 to $35 per hour; countertops range from $3/linear ft. for Plain Jane straight-edged laminates to $100/linear ft. for laminates with a beveled edge that look like granite.
If you’ve planned ahead and stockpiled old tiles, then grab a few and replace cracked or scratched areas. If you don’t have extra tile, then attempt the following first aid:
Stainless steel countertops become scratched, stained, and dull over time. While you’ll never completely remove scratches, you can buff them into a warm patina by massaging with vegetable oil.
Remove stains with a paste of baking soda and dish soap. A sprinkle of Barkeeper’s Friend will remove stains without scratching.
If you are getting ready to sell – call or email me. I would be happy to provide you with a free market analysis of your home. To get your home sold, you need a great marketing plan and accurate pricing. I can give you both!
 Yes, taxes continued. I know, I know…how could we make Friday any more exciting?
The Energy Credit has been a great way to save net money on your home improvements. Looking ahead to this time next year, make sure you are choosing the right places to invest your green money. Washington is giving you less green for going green, as the feds reel back the 2011 energy tax credits from a lavish $1,500 to a paltry $500. Keep your receipts and be ready this time next year.
No matter how much you spend on some approved items, you’ll never get the $500 credit–though you could combine some of these:
| System | Cap |
| New windows | $200 max (and no, not per window—overall) |
| Advanced main air-circulating fan | $50 max |
| Qualified natural gas, propane, or oil furnace or hot water boiler | $150 max |
| Approved electric and geothermal heat pumps; central air-conditioning systems; and natural gas, propane, or oil water heaters | $300 max |
And not all products are created equal in the feds’ eyes. Improvements have to meet IRS energy-efficiency standards to qualify for the tax credit. In the case of boilers and furnaces, they have to meet the 95 AFUE standard. EnergyStar.gov has the details.
Rule of thumb: If installation is either particularly difficult or critical to safe functioning, the credit will cover labor. Otherwise, not. (Yes, you’d have to be pretty handy to install your own windows and roof, but the feds put these squarely in the “not covered” category.)
Installation covered for:
Installation not covered for:
This article provides general information about tax laws and consequences, but isn’t intended to be relied upon as tax or legal advice applicable to particular transactions or circumstances. Consult a tax professional for such advice, and remember that tax laws may vary by jurisdiction.
 What is a Form 5695?? Your energy tax credit! This is a great tax credit that encourages energy upgrades in our homes. Sidestep snares in the complex IRS Form 5695 to get all the 2010 energy tax credits you’ve got coming.
What type of system did you install? If it’s one of the following, complete Part 1 for Nonbusiness Energy Tax Credits.
Max credit: 30% of the cost of the improvement, up to $1,500.
If you installed one of these souped-up systems, complete Part 2 for Residential Energy Efficient Property Credit.
Max credit: 30% of the cost, with no limit except for a kilowatt limit on fuel cells.
For Part I, it’s pretty simple: Just enter the total of all this part’s credits (as shown on line 11) on Form 1040, line 52.
For Part II, it can get complicated because other credits, claimed on other forms, can affect the amount of your Part II credit.
If you need to fill out any of the following forms, have all the information needed to complete those at hand, because Form 5695, line 25, coordinates with all of them. (In fact, you’ll find it simplest to prepare all these forms more or less simultaneously.)
One form that’s irrelevant to completing 5695: Schedule A. That’s only for deductions, not credits. And you don’t even need to itemize to claim energy tax credits.
You’ll find many places you can go wrong in both parts of the form:
Adding ineligible amounts into the form. Just because a product has an Energy Star label doesn’t mean it’s eligible for a credit. Check the details of what’s eligible for the credit and what’s not at Energy Star and make sure the product comes with a manufacturer’s certification.
Failing to keep track of this year’s energy tax credits for future years. Hang on to your tax credit paperwork (including receipts, certifications, and a copy of your completed Form 5695), because if you sell your house you’ll need to record the tax credit amount for tax purposes.
Failing to file this form at all—or only partially. If you’re eligible for a lot of different tax credits, you can conceivably reduce your tax liability to zero. If that’s the case and you want to tack on the 2010 energy tax credit, you’re out of luck. The feds consider it nonrefundable. If it were a refundable tax credit, the IRS would write you a check.
Forgetting certain credits that affect Part II—and vice-versa. Pay special attention to line 25: Certain other credits may ultimately affect your ability to fully claim Part II credits—just as Part II credits may affect other credits. Follow the line-by-line instructions in each form carefully. It’s easy to forget a number here.
If you find Form 5695 exasperating, you may be eligible for free tax preparation help from the:
Major tax preparation software, such as TurboTax, include this form in their packages.
 As promised! More on taxes! I know, I know…it’s crazy to talk about such exciting stuff without a party hat on but an IRS audit or missed refund money is no party either! Here are the ten most common errors that home owners make on their tax returns. Don’t rouse the IRS or pay more taxes than necessary—know the score on each home tax deduction and credit.
You take a tax deduction for property taxes in the year you (or the holder of your escrow account) actually paid them. Some taxing authorities work a year behind—that is, you’re not billed for 2010 property taxes until 2011. But that’s irrelevant to the feds.
Enter on your federal forms whatever amount you actually paid in 2010, no matter what the date is on your tax bill. Dave Hampton, CPA, tax manager at the Cincinnati accounting firm of Burke & Schindler, has seen home owners confuse payments for different years and claim the incorrect amount.
If your lender escrows funds to pay your property taxes, don’t just deduct the amount escrowed, says Bob Meighan, CPA and vice president at TurboTax in San Diego. The regular amount you pay into your escrow account each month to cover property taxes is probably a little more or a little less than your property tax bill. Your lender will adjust the amount every year or so to realign the two.
For example, your tax bill might be $1,200, but your lender may have collected $1,100 or $1,300 in escrow over the year. Deduct only $1,200. Your lender will send you an official statement listing the actual taxes paid. Use that. Don’t just add up 12 months of escrow property tax payments.
Deduct points you paid your lender to secure your mortgage in full for the year you bought your home. However, when you refinance, says Meighan, you must deduct points over the life of your new loan. If you paid $2,000 in points to refinance into a 15-year mortgage, your tax deduction is $133 per year.
Lenders require home buyers with a downpayment of less than 20% to purchase private mortgage insurance (PMI). Avoid the common mistake of forgetting to deduct your PMI payments. However, note the deduction begins to phase out once your adjusted gross income reaches $100,000 and disappears entirely when your AGI surpasses $109,000.
This deduction may not be as good as it seems. It often doesn’t amount to much of a deduction, has to be recaptured if you turn a profit when you sell your home, and can pique the IRS’s interest in your return. Hampton’s advice: Claim it only if it’s worth those drawbacks.
If you met the midyear 2010 deadlines, don’t forget to take this tax credit into account when filing.
Even if you missed the 2010 deadlines, you still might be in luck: Congress extended the first-time home buyer credit for military families and other government workers on assignment outside the United States. If you meet the criteria, you have until June 30, 2011, to close on your first home and qualify for the tax credit of up to $8,000.
If the IRS comes a-knockin’, don’t be scrambling to compile your records. Many people forget to track home office and home maintenance and repair expenses, says Meighan. File away documents as you go. For example, save each manufacturer’s certification statement for energy tax credits, insurance company statements for PMI, and lender or government statements to confirm property taxes paid.
If you sold your main home last year, don’t forget to pay capital gains taxes on any profit. However, you can exclude $250,000 (or $500,000 if you’re a married couple) of any profits from taxes. So if you bought a home for $100,000 and sold it for $400,000, your capital gains are $300,000. If you’re single, you owe taxes on $50,000 of gains. However, there are minimum time limits for holding property to take advantage of the exclusions, and other details. Consult IRS Publication 523.
If you made any eligible improvement, fill out Form 5695. Part I, which covers the 30%/$1,500 credit for such items as insulation and windows, is fairly straightforward. But Part II, which covers the 30%/no-limit items such as geothermal heat pumps, can be incredibly complex and involves crosschecking with half a dozen other IRS forms. Read the instructions carefully. More on the energy tax credits to come!
You can deduct mortgage interest only up to $1 million of mortgage debt, says Meighan. If you have $1.2 million in mortgage debt, for example, deduct only the mortgage interest attributable to the first $1 million.
This article provides general information about tax laws and consequences, but is not intended to be relied upon by readers as tax or legal advice applicable to particular transactions or circumstances. Readers should consult a tax professional for such advice, and are reminded that tax laws may vary by jurisdiction.
 Yes it’s that time of year again! The snowbanks are getting higher and taking on a “brownish” tint – the joy of winter has passed with the holiday season and we’re all looking forward to spring – why not spend this time doing something fun! Like taxes! Woot! No really…it’s a chore but it’s necessary and as a taxpayer you are entitled to every deduction available to you. That’s right, the IRS WANTS you to have an accurate number for your total tax liability.
This week I will have a series of articles on “Don’t Miss Tax Breaks” for home owners. I have a financial background as a CPA prior to becoming a Realtor. This is great stuff and I welcome your comments.
Get an “A” on your Schedule A Form: Dodge these tax deduction pitfalls to save time, money, and an IRS investigation.
Your monthly mortgage payment often includes money for a tax escrow, from which the lender pays your local real estate taxes.
The money you send the bank may be more than what the bank pays for your taxes, says Julian Block, a tax attorney and author of Julian Block’s Home Seller’s Guide to Tax Savings. That will lead you to putting the wrong number on Schedule A.
Example:
Now do the math:
If you bought or sold a home in the middle of 2010, figuring out what to put on line 6 of your Schedule A Form is tricky.
Don’t simply enter the number from your property tax bill on line 6 as you would if you owned the house the whole year. If you bought or sold a house in midyear, you should instead use the property tax amount listed on your HUD-1 closing statement, says Phil Marti, a retired IRS official.
Here’s why: Generally, depending on the local tax cycle, either the seller gives the buyer money to pay the taxes when they come due or, if the seller has already paid taxes, the buyer reimburses the seller at closing. Those taxes are deductible that year, but won’t be reflected on your property tax bill.
You can deduct points paid on a refinance, but not all at once, says David Sands, a CPA with Buchbinder Tunick & Co LLP. Rather, you deduct them over the life of your loan. So if you paid $1,000 in points for a 10-year refinance, you’re entitled to deduct only $100 per year on your Schedule A Form.
If you took out a home equity line of credit (HELOC), you can generally deduct the interest on it only up to $100,000 of debt each year, says Matthew Lender, a CPA with EisnerLubin LLP.
For example, if you have a HELOC for $200,000, the bank will send you Form 1098 for interest paid on $200,000. But you can deduct only the interest paid on $100,000. If you just pull the number off Form 1098, you’ll deduct more than you’re entitled to.
You can deduct PMI on your Schedule A Form, as long as you started paying the insurance after Dec. 31, 2006. (Also, this is also a good time to review your PMI: You might be able to cancel your PMI altogether because you’ve had a change in loan-to-value status.)
You can deduct part or all of losses caused by theft, vandalism, fire, or similar causes, as well as corrosive drywall, but the process isn’t always obvious or simple:
Bottom line on line 20: If you’ve got extensive losses, it’s best to consult a tax pro. “I wouldn’t do it myself, and I’ve been dealing with taxes for 40 years,” says former IRS official Marti.
I know…not very exciting but necessary!